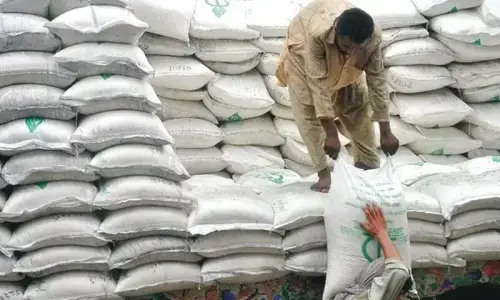
KARACHI: The saga of Lafarge Pakistan Cement Limited sale came to an end on Thursday, when Bestway Cement Limited (LPCL) sealed the deal for buyout of 75.86 per cent shares in the cement company held by the parent Safimo SAS, for purchase consideration of $218 million.
The sale price corresponded to an enterprise value (EV) of 100pc at $329m. The deal is subject to adjustments specified in the Share Purchase Agreement and regulatory approvals.
Analyst Vahaj Ahmed calculated that at Rs33bn enterprise value, the price per share worked out at Rs19.50.
Bilal Alvi, investment analyst at AKD Securities affirmed that with the acquisition, Bestway would emerge as the largest cement manufacturer in Pakistan with a capacity of 8.3m tonnes.
Lafarge Cement to remain unimpaired by parent deal
Ayesha Khokhar, company secretary LPCL, confirmed that the company was informed by Sofimo SAS (the holding company for the main subsidiaries of the Lafarge Group) as indirect holder of approximately 75.86pc shares of the company of the close of deal with Bestway Cement.
LPCL also unveiled letter written by Jerome Virulo, authorised reprentative for Societe Financiere Immobiliere ET Mobiliere SAS (SOFIMO) to Amir Reda, CEO at LPCL, informing about the binding share purchase agreement with Bestway Cement, dated July 23, 2014.
Although a few parties had walked away after an initial expression of interest in the LPCL acquisition, four groups that remained in the race for bidding of buyout of majority holding and control of LPCL included Vision Holding Middle East Limited (VHMEL); Bestway Cement; DG Khan Cement and Kohat Cement.
Although two bidders Bestway and DG Khan Cement were shortlisted for final evaluation, most market players had put the money on table in favour of DGKC emerging as the winner.
Analysts at Taurus Securities thought that DGKC may opt for a green field cement expansion project in which it had previously shown interest for expansion in the Southern Zone. But with LPCL acquisition in the pipeline, market experts thought that if DGKC acquires LPCL, it may drop the idea of going into expansion. The company was now likely to review that decision.
The total number of issued shares of LPCL stands at 1.45bn of Rs10 each. The sale-purchase deal has been sealed for 1.10bn shares, constituting 75.86pc of the total paid up capital of the company.
For the minority shareholders in LPCL, the mandatory tender offer by the buyer for remaining shares would be of interest. Vahaj at Topline says: “As per regulations, the tender price has to be at least the acquisition price, i.e. Rs19.50. Thus an investor can make annualised gain of 8pc from current levels; assuming 70pc shares are accepted in tender and the shareholder can sell remaining 30pc in the market at LPCL’s fair price at Rs12 per share.”
Published in Dawn, July 25th , 2014