Pakistan ‘will absolutely not default’, asserts Dar


Finance Minister Ishaq Dar on Wednesday asserted that the country was not on the verge of a financial crisis and “will absolutely not default”.
Dar’s remarks comes amid growing fears of default, propelled by the country’s declining remittances and foreign exchange reserves, as well as a prolonged delay in reaching an accord with the International Monetary Fund for the release of a $1.1 billion tranche out of a $6.5bn loan package.
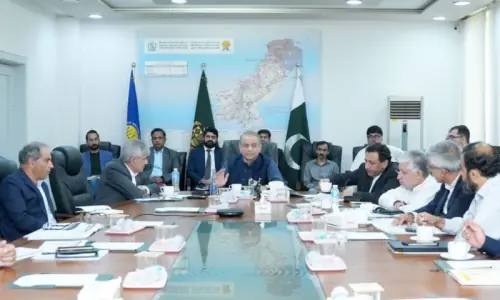
Addressing the fears during a gathering at the Federal Board of Revenue in Islamabad, the finance minister commended his economic team for its “efforts and hard work”, pointing out that the country had recorded a current account surplus for the months of March and April at $750 million and $18m, respectively.
Regarding the ongoing negotiations with the IMF for release of the long-awaited bailout tranche, Dar said his team had completed all the technical work and prior actions required for the completion of the ninth review.
He stressed that there was a “sincere effort” on his and his team’s part to complete the IMF’s ongoing programme and said they delay was “unfortunate”.
The review should have been completed earlier, he added.
Dar said the country had repaid $5.5 billion of its commercial loans. Of those, he said China had rolled over $2bn once it “understood” that Pakistan had completed its requirements for the release of funds by the IMF.
Regarding the rest of the $3.5bn from non-Chinese commercial banks, Dar said: “We are expecting that a substantial part of that [loan] facility will be returned once the [IMF] staff level agreement or board meeting is completed because it is always renewed and they (banks) are always there to do business.”
Delay in IMF accord
A staff-level accord to release a $1.1bn tranche out of a $6.5bn IMF package has been delayed since November, with over 100 days gone since the last staff-level mission to Pakistan. That is the longest such gap since at least 2008.
The international money lender said earlier this month that Pakistan needed significant additional financing for a successful completion of the long-stalled ninth review of the IMF’s bailout package.
Obtaining commitments of “significant additional financing” is essential before the IMF approved the release of pending bailout funds that are crucial for the country to resolve an acute balance of payments crisis, it added.
So far, the United Arab Emirates, Saudi Arabia and China have come to Pakistan’s assistance in March and April with pledges that would cover some of the funding deficit.