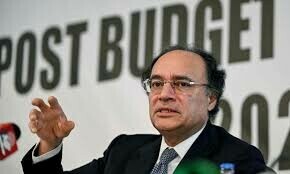
FINANCE Minister Muhammad Aurangzeb has once again contended that ‘Pakistan is heading in the right direction’, conceding the urgency of securing external financing for the approval of its $7bn bailout package by the IMF executive board.
His recorded address was broadcast amid further delays in the approval of the facility by the board, at least until the middle of this month, because of the country’s failure to secure a timely rollover of $12bn in loans from China, Saudi Arabia, and the UAE, as well as arrange $2bn in commercial loans to fill the financing hole for the present fiscal.
The staff-level agreement was concluded on July 15, with the minister hoping to get IMF board approval for the fresh deal by middle of last month. The same day PM Shehbaz Sharif said his government was working on implementing conditions from the IMF but did not elaborate.
Likewise, the minister also spent a better part of his speech on ‘positive economic developments’ — like slowing inflation, closing current account gap, stable exchange rate, falling interest rates, improving reserves — achieved over the past six months, yielding real results in macroeconomic stability, rather than explaining the reasons behind the delays in confirmation of the debt rollovers by the friendly countries.
Pakistan’s economy has long been in the grips of financial instability, characterised by rising debt burden, stagnating growth, widening fiscal deficit, and recurring balance of payments crises, which force it to take recourse to heavy external borrowing to avert default on its foreign payments.
The country’s addiction to foreign loans to pay its bills has forced many to raise critical questions about its financial future and economic sustainability. The authorities’ reliance on short-term loans and debt rollovers from friendly states has become a recurring theme in the national economic narrative for the last several years. Even the success of a government in general and finance minister in particular is judged on the basis of their ability to deal with and borrow from multilateral and bilateral lenders. It was one of the reasons Mr Aurangzeb was chosen over Ishaq Dar for his present job.
It’s no secret that debt rollovers and the IMF provide temporary relief but do not repair the underlying structural faults in the economy. The fragility of the present economic stability illustrates this quite clearly. The macro numbers have improved, but at a massive cost to people and growth. Even the IMF dollars and bilateral debt rollovers will not enable us to push for growth beyond 3-3.5pc, or we might again be led into another balance of payments crisis.
The only way forward towards long-term economic stability, growth and debt-free prosperity lies in broadening the tax revenue base, increasing and diversifying exports, and attracting sustainable foreign direct investment. No shortcuts will work this time around.
Published in Dawn, September 5th, 2024