Pakistan’s chemical industry is a foundational pillar of the country’s manufacturing base, supplying essential inputs to textiles, construction, agriculture, pharmaceuticals, packaging and numerous other sectors.
Its broad base includes basic and inorganic chemicals such as caustic soda, soda ash, and chlorine, alongside polymers and resins like polyvinyl chloride (PVC), industrial gases, speciality chemicals, paints, and oleochemicals.
Pakistan Chemical Manufacturers Association (PCMA) estimates the domestic chemical and petrochemical market at over $14 billion annually, with 56 per cent of demand currently met through imports. The Pakistan China Joint Chamber of Commerce and Industry has projected that the market could potentially reach $20bn with continued growth in large-scale manufacturing.
The sector contributes about 3pc of GDP, according to an investment pitchbook prepared by the Consulate General of Pakistan in Guangzhou, while industry officials put the figure at 3-4pc. The industry also provides hundreds of thousands of direct and indirect jobs. The PCMA estimates that an integrated petrochemical value chain could generate over 100,000 additional jobs and support downstream industrial output exceeding $50bn.
The industry provides primary inputs for virtually every manufacturing segment
Its economic linkages are equally significant. Chemicals are primary inputs for virtually every manufacturing segment, including pharmaceuticals, automobiles, textiles, furniture, paints, paper, electronics and appliances. Textile and paper producers, for example, depend on caustic soda, while construction uses soda ash and sulfuric acid.
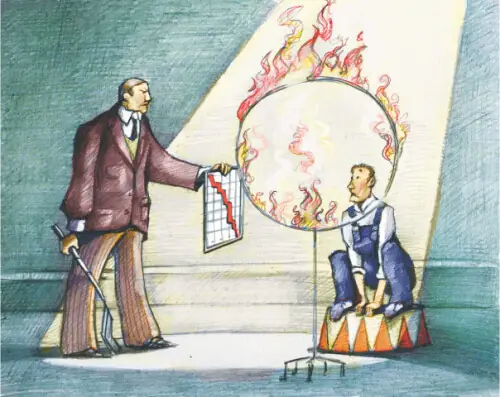
Yet the industry presents a paradox. Despite substantial domestic demand, locally available minerals and an established manufacturing base, Pakistan remains heavily dependent on imported chemicals and petrochemical intermediates.
Pakistan Bureau of Statistics figures indicate that domestic chemical production, excluding categories such as fertilisers and pharmaceuticals depending on classification, declined from around 3.8 million tonnes in FY25 to roughly 3.4m tonnes in FY26. The chemical component of large-scale manufacturing has also remained under pressure.
Imports account for around 56pc of chemical demand, with dependence particularly high in basic, intermediate and speciality chemicals. Pakistan consequently imports petrochemical feedstocks, intermediates, plastics, PTA [Purified Terephthalic Acid], organic chemicals and speciality products, generating an import bill running into several billion dollars, depending on classification. This dependence is also an opportunity, though. Every chemical that can be produced competitively at home represents potential import substitution.
There are some encouraging signs. Chemical and pharmaceutical exports were around $1.45bn in FY25 and $1.32bn in FY26 under the relevant State Bank classification. Chemical exports to China reportedly rose 201pc to $13.19m during the first half of 2025, from $4.38m in the corresponding period of 2024.
The larger opportunity lies in converting domestic resources into higher-value products for both local and regional markets. Afghanistan, the Middle East, East Africa, Sri Lanka, Bangladesh and Central Asia could provide outlets for PVC, caustic soda, industrial chemicals and other value-added products.
Policy attention has increased recently. The Special Investment Facilitation Council has promoted projects involving agro-chemicals, speciality chemicals, coatings, adhesives and water-treatment chemicals. The government has also encouraged foreign joint ventures and investment in special economic zones.
But investment facilitation alone cannot create a competitive chemical industry. Investors need certainty over feedstock availability and prices, energy costs, taxation, environmental approvals, customs arrangements and tariffs.
This exposes a major policy gap. Pakistan still lacks a single, comprehensive national chemical or petrochemical policy bringing together investment, feedstock, energy, tariffs, taxation, research, exports, technology and environmental regulation. Instead, these issues are addressed through separate policies, ministries and initiatives.
Some progress is visible in petroleum refining. The revised Brownfield Refining Policy provides incentives for existing refineries to modernise, improve fuel quality and increase production. In September 2026, Attock Refinery, National Refinery, Pakistan Refinery and Cnergyico signed upgrade agreements involving $5bn over five years.
Refinery modernisation could strengthen the foundation for downstream petrochemicals, but refinery upgrades and a petrochemical policy are not the same thing. Pakistan needs a defined chain linking crude refining to petrochemical feedstocks, basic chemicals, polymers and higher-value downstream products.
The proposed naphtha-cracking complex illustrates the opportunity. A domestic cracker could produce petrochemical building blocks for plastics, packaging, textiles and other industries, reducing imports and stimulating downstream manufacturing. But such a project requires dependable feedstock, competitive energy, infrastructure, financing and a sufficiently large downstream market, alongside a durable incentive structure.
Tariff and industrial reforms can address some constraints. The proposed National Industrial Policy seeks to improve access to energy, finance, industrial land and special economic zones, while tariff reforms aim to rationalise duties on machinery and industrial inputs.
Environmental regulation must form another pillar. Pakistan already has a National Hazardous Waste Management Policy, while stronger chemicals management, controls on hazardous substances and internationally recognised classification and labelling systems have also been discussed.
For a market potentially approaching $20bn, the opportunity is too large to remain fragmented. Tapping it requires more than encouraging individual projects; it requires building a value chain connecting raw materials, industrial capacity and domestic demand to competitive production and exports.
Published in Dawn, The Business and Finance Weekly, October 5th, 2026