It might seem strange to worry about an economy that grew 7.4 per cent last year, but despite - or rather, because of - that good news, Turkey is showing all the classic signs of an emerging markets crisis.
It’s pretty simple. Turkey has and continues to borrow a lot of dollars that are getting harder to pay back now that its currency is falling fast. Or, more specifically, its banks and companies have. But, in any case, the fact that its government hasn’t built up a big rainy-day fund of dollars has left it with a catch22: Turkey can either try to save its economy from the effects of a weaker currency by increasing interest rates, or from the effects of higher interest rates by allowing its currency to continue dropping. Which is to say that it really has to decide how it doesn’t want to save things.
But even though there are no good choices here, there are worse ones. Higher rates might slow the economy down enough that some companies would get into trouble, but a weaker currency would make that even more likely by increasing their debt burdens, potentially setting off a self-fulfilling panic. Foreign investors, after all, would pull even more money out of the country if they saw Turkish businesses going under - they’ve already been moving it out in response to the Federal Reserve’s rate hikes that have made holding money in the United States more attractive - which would then push their currency down even more, and, as a result, send even more companies into default.
The prospect of this, of course, would make it hard for the Turkish banks that would be on the hook for these losses to borrow money themselves. So they’d have to cut back on their lending, and maybe even get a bailout - a bailout that, if history is any guide, would probably require them to, yes, increase interest rates to try to stabilise the currency. It would be better, then, to skip all that extra pain, and just get the rate hikes out of the way now.
It’s not clear if they will, though.
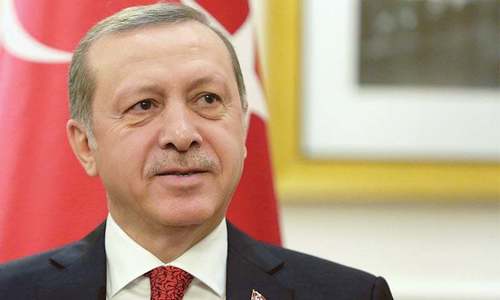
The problem is that Turkey’s increasingly autocratic president, Recep Tayyip Erdogan, has a bad habit of mistaking correlation for causation. In particular, he thinks that low interest rates cause low inflation, which, as economist Andy Harless has put it, is akin to believing that umbrellas cause rain. Low inflation, you see, allows central banks to keep interest rates low, but that doesn’t mean that keeping interest rates low will lead to low inflation. The opposite, actually.
Erdogan, though, apparently hasn’t noticed. Empirical reality doesn’t seem to interest him as much as the one he’s trying to create. And so he has insisted that high interest rates are the “mother and father of all evil” and that anyone - like, say, their central bankers - who tries to force them on the country is guilty of “treason.”
Now, up until this week, it was possible to tell yourself that this might just be extreme cynicism. That Erdogan didn’t really think that low interest rates cause low inflation, but was just saying so to try to pressure the central bank into keeping them down ahead of last month’s elections - and with good reason. For all the power he’s consolidated, Erdogan was only able to secure 52pc of the most recent vote.
That’s about as unimpressive as it gets when you’ve just purged the media, schools, army, and businesses of everyone but the most servile and supine; when you control the media to such a degree that your opponents could barely even get covered; and when you actually threw one opposition leader in jail. All of which explains why Erdogan was so intent on goosing growth up to 7.4pc last year and trying to keep it going this one, even if it came at the cost of so much debt and inflation that it seemed as if it was inevitably setting them up for a crash some time soon.
But it’s hard to tell yourself that anymore. That’s because Erdogan seems no less committed to his wacky theories today than he did before the election. He just appointed his son-in-law to run the country’s finance and treasury departments - what sure looks like a rubber stamp in human form - and, after giving himself the power to choose the country’s top central banker, he “predicted” that “in the period ahead I believe that we will see that interest rates also fall.” It was enough to send the Turkish currency, the lira, down another 6.5pc this week alone to bring it 23.7pc lower than it was at the start of February.
An economy, like a mind, is a terrible thing to lose. Erdogan appears well on his way to losing both.
Published in Dawn, July 14th, 2018