Should Pakistanis not have the right to invest in the country’s large public interest licensed companies?
To help answer this question, think about commercial banks. They tend to be large and cannot start their business without a banking licence. There is substantial public interest at stake in these banks: they touch the lives of millions every day, while a bank in trouble also drags its stakeholders into trouble.
It is not a coincidence that commercial banks are listed at the Pakistan Stock Exchange (PSX), it is a requirement laid down by the State Bank of Pakistan (SBP).
Listing triggers a set of corporate governance requirements which is generally not applicable to unlisted companies; and research by investment analysts, and pricing through open market trading, signals company health to the regulator and stakeholders.
Above all, it is because of the listing of commercial banks that Pakistanis are able to invest in their shares, either through direct share purchase or indirectly through mutual and pension funds. Today, these banks account for a nearly a fifth of market capitalisation at the PSX and are widely represented in equity portfolios.
Listing also helps reduce pressure on balance of payments, a major issue for Pakistan. When most of a company’s shares are owned by foreigners, its partial domestic ownership means there will be proportionately less dividend repatriation abroad.
That’s why large public interest companies operating on a special purpose license ought to be required to list on the PSX. These companies will offer at least 25 per cent
shares to the general public under the exchange’s listing regulations; the remaining shares will stay in the hands of the existing owners while the newly-listed company will get additional capital to grow its business.
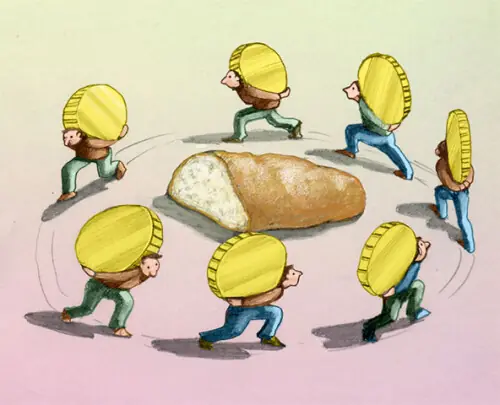
Ownership of public interest companies by ordinary Pakistanis will bring greater social relevance to licensing, which appears to be a bureaucratic affair disconnected from our society.
Public interest is not confined to commercial banks just as financial services companies are not the only example of licensed companies. There are other large licensed companies with substantial public interest including those in the telecom and oil and gas sector.
There are also large public interest licensed companies attracting investment under CPEC and hopefully it is not too late to consider listing them.
According to the G20/OECD principles of corporate governance, “Stock markets can play a meaningful role in enhancing corporate governance by establishing and enforcing requirements that promote effective corporate governance by their listed issuers.”
Notice that it says “issuers”, not financial institutions. That is, the governance benefits of listing are not specific to financial services companies.
Some of the large licensed public interest companies have become household names, such as the unlisted giants from the telecom sector: Telenor Pakistan, Jazz, China Mobile Pakistan (Zong), and Pak Telecom Mobile (Ufone).
Let’s now try to see things from the perspective of the companies. Why do many large public interest licensed companies choose to stay unlisted?
Most state that listing is a commercial matter and companies should not be required to share corporate control. They argue that listing is not a panacea for good governance as there are some listed companies that have worse governance than unlisted ones.
Another argument is that mandatory listing is better applied to State Owned Companies (SOEs), such as State Life, the largest life insurer in Pakistan. They highlight the fact that the shareholder base in Pakistan is particularly narrow and express the fear that listing as a licensing condition could discourage foreign investment in the country.
There is some merit to these arguments but they do not override the right of Pakistanis to invest in these companies.
To begin with, the precedent of a mandatory listing of commercial banks shows that listing is not always a commercial matter. As for panacea, there never was one anywhere. Listing strengthens governance of an unlisted company; it is a higher standard, not a silver bullet.
There is no disagreement that the same principle should apply for SOEs and State Life is a good example. But that does not mean that the principle be confined to them.
Regarding investor base, these share offerings can easily be structured in a way that preference is given to the ordinary Pakistanis applying for the smallest lot at a reasonable price.
Finally, if threats as large as political instability, terrorism, and corruption do not discourage foreign investors from investing in Pakistan, a requirement to list at the PSX is unlikely to keep them away.
This debate is far from academic. Public interest companies have been defined in the Companies Act, 2017 using criteria that include SOEs, nature of business (e.g. utilities), size of assets, and number of shareholders. Under section 216 of this Act, the SECP has the mandate to impose additional disclosure on a public interest company. Moreover, under section 20 of the Securities Act, 2015, in view of public interest, SECP has the power to direct PSX to list the shares of a company.
That’s not all. The licensing laws of key regulators, such as Ogra, PTA, Nepra, and Pemra also refer to “public interest” even if they currently do not require listing as a licensing condition.
— The writer is a former executive director at the Securities and Exchange Commission of Pakistan
Published in Dawn, The Business and Finance Weekly, December 11th, 2017