FCC reserves ruling on petitions challenging Super Tax judgement
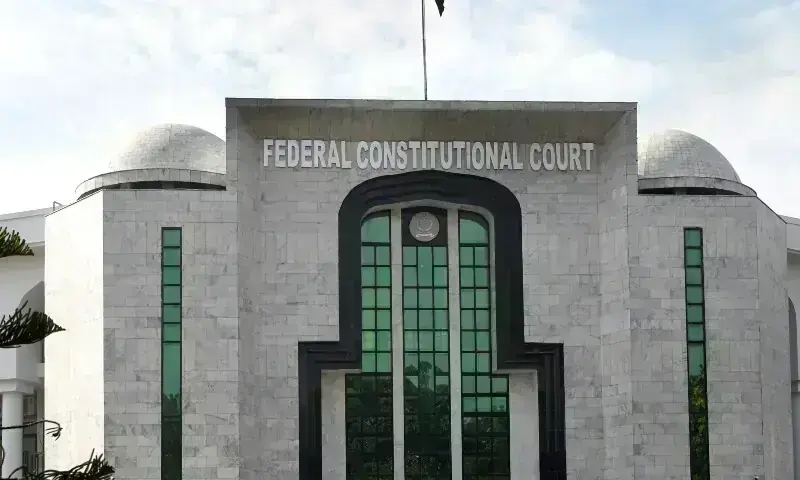
ISLAMABAD: The Federal Constitutional Court (FCC) on Monday reserved its ruling on a set of petitions seeking a review of its Jan 27 judgement upholding the vires of the Super Tax, while highlighting that Sections 4B and 4C of the Income Tax Ordinance (ITO), 2001, would apply from the dates on which they were levied.
Headed by Chief Justice Aminuddin Khan, a three-judge FCC bench, comprising Justice Syed Hasan Azhar Rizvi and Justice Syed Arshad Hussain Shah, also took up a set of review petitions seeking to revisit the Jan 27 judgement. In that ruling, the court had declared that the legislature was fully competent to impose, abolish, remit, alter or regulate such a tax through a Finance Act as part of a Money Bill under Article 73(2)(a) of the Constitution.
Consequently, a number of companies, including Fauji Fertiliser Company Ltd, Fauji Fertiliser Bin Qasim (Pvt) Ltd, Thar Power Company Ltd, M/s Pacific Exim (Pvt) Limited, Agven (Pvt) Limited, Jubilee Corporation, Colgate-Palmolive Pakistan Limited, M/s Chawla International, Karachi, The Searle Company Limited, JS Bank Ltd, Karachi, Total Parco Pakistan Limited, JWD Sugar Mills Ltd, Gas & Oil Pakistan Ltd, Defence Housing Authority, Lahore, Hoechst Pakistan Limited, Arif Habib Corporation Limited, Habib Metro Pakistan (Pvt) Ltd, Pak Arab Fertilizer Limited, Pakistan Refinery Limited, Engro Corporation Ltd and several others, filed review petitions against the judgement.
On Monday, several senior counsel, including Dr Farogh Nasim, Khalid Javed Khan, Sardar Ahmed Jamal Sukhera, Rashid Anwar and Imtiaz Ali Siddiqui, presented their arguments.
Taxpayers challenge retrospective imposition of the tax on constitutional grounds
Introduced by the PML-N government in 2015, the Super Tax applies to wealthy individuals, associations of persons and companies earning more than Rs500 million. It imposes a tax rate of 4 per cent on the income of banking companies and 3 per cent on other sectors, with the stated aim of funding the rehabilitation of temporarily displaced persons.
Sardar Ahmed Jamal Sukhera, who represented one of the petitioners, Fauji Fertilisers, told Dawn that, after a day-long hearing on Monday, the FCC bench had reserved its ruling on the review petitions.
The counsel urged the top court to strike down Section 4C of the ITO as unconstitutional, arguing that no reasons had been given for upholding the provision in its Jan 27 judgement.
Alternatively, the FCC should declare that Section 4C did not apply to tax year 2022 and did not extend to income subject to final tax. It should also exclude brought-forward losses, depreciation and amortisation, he argued.
Sukhera contended that the Finance Act, 2022, took effect on July 2, 2022, and imposed a tax charge on income earned in a tax year that had already closed. By then, taxpayers had closed their accounts, held their annual general meetings and distributed dividends under the prevailing law. A liability that could not have been foreseen when the income was earned and applied was arbitrary and wholly unreasonable, he argued.
Highlighting the stated objective behind the levy, the counsel said it was intended to raise about Rs215 billion. However, the record showed that losses incurred by state-owned enterprises alone amounted to a staggering Rs650 billion a year, while electricity theft resulted in annual losses of about Rs600bn. Continued federal spending on devolved subjects amounted to about Rs328 billion, while borrowing beyond the limits prescribed by the Fiscal Responsibility and Debt Limitation Act, 2005, from a single treasury account amounted to Rs404bn.
The review petition argued that the FCC had overlooked the fact that the retrospective imposition of a fresh tax charge was constitutionally barred under Articles 10A, 18, 23 and 24 of the Constitution, which placed restrictions on Parliament’s legislative powers.
Likewise, the denial of the right to carry forward losses and depreciation or amortisation amounted to imposing income tax on expenses or losses, which was impermissible under Entry 47, allowing the federation to tax income only, the petition argued.
Published in Dawn, November 3rd, 2026