FCC sets aside Income Tax Ordinance section enabling taxation on ‘deemed income’ from assets and property
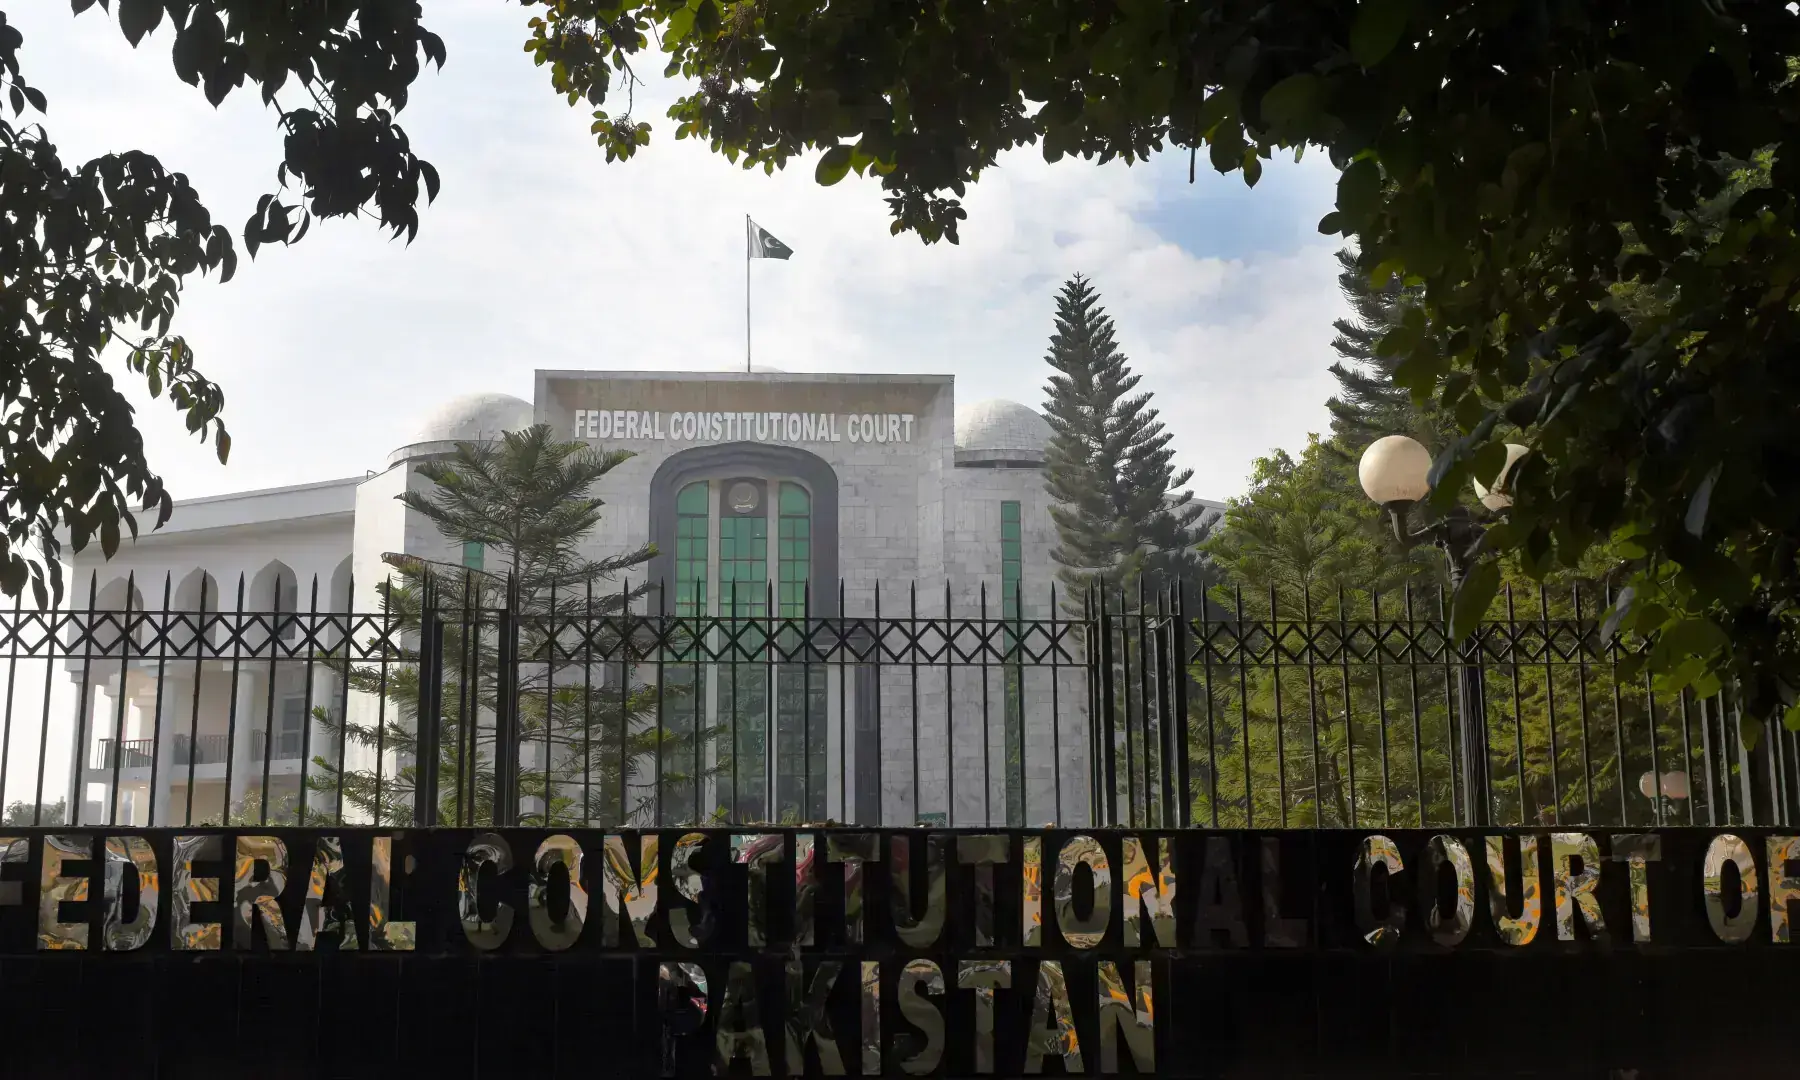
ISLAMABAD: The Federal Constitutional Court (FCC) on Thursday set aside Section 7E of the Income Tax Ordinance (ITO) 2001 as ultra vires the Constitution, which had empowered tax authorities to levy tax on “deemed income” from assets and properties.
Having a significant impact on the Federal Board of Revenue’s (FBR) property taxation, Section 7E was introduced through the Finance Act, 2022, for the tax year 2023.
It provided for taxation on deemed or notional income arising from ownership of certain immovable properties, subject to specified exemptions relating to personal residences, agricultural land, and other exempt categories recognised under the statutory framework.
The Finance Act 2022 had imposed tax on the “deemed income” of taxpayers holding immovable property worth over Rs25 million. The provision taxed such property at five per cent of its FBR-defined fair market value, subject to a 20 per cent tax rate, resulting in an effective annual tax of one per cent on the capital value of undeveloped or non-rented properties.
“Having heard the learned counsel for the parties at considerable length and upon due deliberation, we are persuaded to hold that Section 7E of ITO, 2001, is ultra vires the Constitution and is accordingly struck down, being void ab initio,” said a short order announced in an open court by a two-judge FCC bench consisting of FCC Chief Justice Aminuddin Khan and Justice Ali Baqar Najafi.
The detailed reasons will be recorded separately, the judgment said.
The FCC, however, converted the civil petitions filed by a number of taxpayers against the judgments of the Sindh High Court (SHC) and the Lahore High Court (LHC) into appeals and allowed them.
However, the civil petitions filed by the FBR and the Commissioner Inland Revenue (CIR) against the judgments of the Peshawar High Court (PHC) and the Balochistan High Court (BHC) were dismissed.
Consequently, all actions, proceedings, and notices initiated or taken by the FBR under Section 7E were declared to be without lawful authority and set aside, the short order explained.
The insertion of Section 7E in ITO was assailed before all the provincial high courts, including the Islamabad High Court (IHC), on constitutional grounds.
The PHC and BHC declared the impugned provision to be ultra vires the Constitution and struck it down. The IHC did not invalidate the provision in its entirety, and read it down to declare subsection (2) to be ultra vires the Constitution.
Against the judgment of the single judge of the IHC, Intra-Court Appeals (ICA) were pending before the division bench of IHC in addition to two writ petitions, which were requisitioned through an April 6, 2026, order in the light of Article 175E (5) of the Constitution after the 27th Amendment. These were transferred to the FCC.
One LHC judge allowed the writ petitions; however, the said judgment was reversed in ICAs by a division bench, which allowed the appeals and dismissed the petitions. The SHC similarly dismissed the constitutional petitions.
Consequently, the taxpayers assailed the judgments of the LHC and the SHC, whereas the federal government, FBR and CIR challenged the judgments rendered by the PHC, BHC and IHC.
The petitions had challenged the provision on the grounds that it imposed tax on deemed income irrespective of actual accrual or receipt of income.
Counsel for the petitioners during the hearing argued that the provision effectively amounted to a property tax disguised as income tax, thereby exceeding Parliament’s legislative competence under Article 77 read with Entry 47 of the Federal Legislative List.
The petitions had contended that the provision created artificial income without realisation and violated Article 25 of the Constitution by introducing arbitrary classifications among taxpayers.
On the other hand, the federation defended Section 7E as a valid fiscal measure intended to broaden the tax base and address untaxed economic capacity.
They argued that deemed income was a recognised legal fiction in taxation jurisprudence and fell within Parliament’s constitutional authority to levy taxes on income.