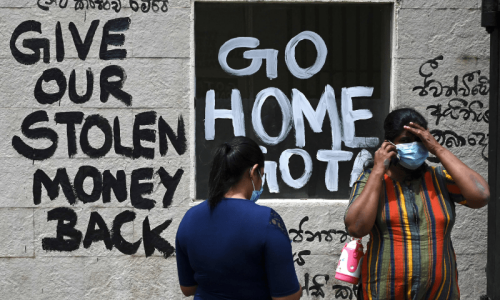Sri Lanka freezes govt recruitment in fresh austerity drive


Sri Lanka began a fresh austerity drive on Monday, freezing government recruitment as new taxes and higher electricity prices kicked in with authorities trying to secure a bailout from the International Monetary Fund (IMF).
The Indian Ocean island nation needs to achieve debt sustainability as a precondition to a $2.9 billion bailout from the Washington-based lender after it defaulted in April as its economy went into crisis.
The IMF has also asked Colombo to trim its 1.5 million strong public service, sharply raise taxes and sell off loss-making state enterprises.
A record 20,000 civil servants retired at the end of December — eight times as many as usual according to the public administration ministry — after President Ranil Wickremesinghe reduced their retirement age from 65 to 60.
They will not be replaced, the ministry said.
Doubled personal income and corporate taxes kicked in on New Year’s Day to shore up state revenue, while electricity prices went up 65 per cent after a 75pc tariff increase in August.
Wickremesinghe, who came to power after Gotabaya Rajapaksa fled the country and resigned in July following months of protests, said the crisis was not yet over despite the restoration of fuel, food and fertiliser supplies.
“Our problems have not been resolved yet,” he told his staff on the first working day of the year.
“We need to reduce our debt burden if we are to move forward.”
Key creditors such as China and India are yet to announce an agreement to a “haircut” on their loans to the South Asian nation.
As part of the new measures, the finance ministry has also banned non-essential capital expenditure.
Any officials who authorise investments over 500m rupees ($1.38m) without clearing them with the treasury first will be held personally accountable, a ministry official said.
At the height of the economic crisis six months ago, motorists spent days in long queues to top up fuel tanks while the country endured 13-hour electricity blackouts and food inflation hit nearly 100pc.