Inflation as a fiscal problem
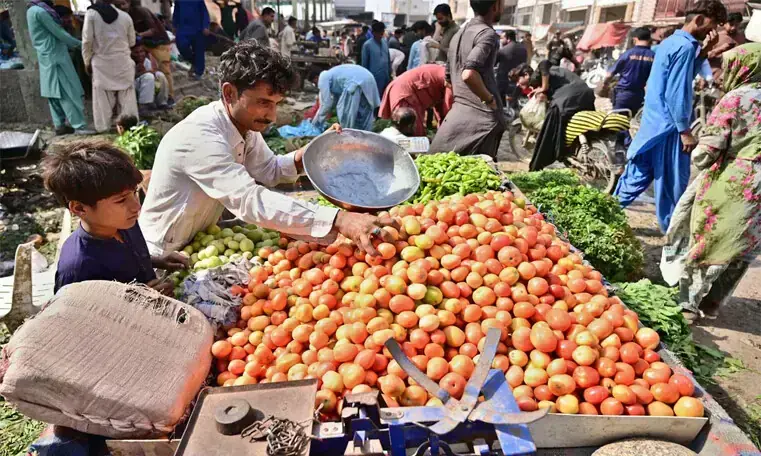
Amid the post-Covid 19 massive inflationary spiral, the fiscally suffocated government, with limited days of foreign exchange reserves, became dependent on the domestic debt market to finance its massive deficits amid rising inflation. Therefore, it had to issue a massive amount of floating-rate, long-tenor debt instruments to manage extreme rollover risk.
For reference, the total cumulative issuance of semi-annual floating Pakistan Investment Bonds increased from less than Rs1 trillion in 2020 to more than Rs14tr in 2024, and is currently more than Rs22tr. Floating rate instruments constitute approximately 70 per cent of all domestic sovereign debt. The debt portfolio’s Average Time to Maturity (ATM) is near 3.9 years, while Average Time to Refix (ATR) stands just above one year. This leads to a vicious cycle of repricing: price increases immediately upset fiscal accounts.
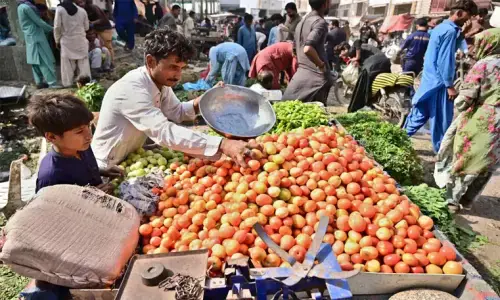
The conventional economic theory believes price spirals are the result of excess aggregate demand that the State Bank of Pakistan can tame by raising interest rates. However, Pakistan has high cost-push, structural, and import-driven inflation. The recurring price spirals are mainly on the supply side and are the result of sudden currency devaluation, global commodity shocks, frequent revisions of administered energy tariffs to offset energy sector circular debt and domestic food supply bottlenecks.
In this structural context, the monetary policy measures taken by the State Bank of Pakistan are certainly needed. In the absence of a hawkish monetary policy amid an inflationary wave, inflationary expectations quickly get out of hand, second-round wage-price spirals set in, and exchange rate pressures build up, potentially leading to an uncontained macroeconomic spiral. But the central bank’s tightening directly affects the most important channel that links inflation to an overwhelming fiscal burden: the domestic cost of debt.
The government should continue to work on structural reprofiling to address the sovereign portfolio’s repricing sensitivity
The correlation between debt servicing and headline inflation in the period 2006-16 was negligible and became moderate to strong post the 2022-23 spiral. The central bank’s rate hike to tackle price shocks reprices the government’s huge domestic floating debt stock. This means that the policy rate hikes get quickly and vigorously passed on through the sovereign debt portfolio to fiscal expenditures. This transmission is a delayed pass-through, with the sensitivity of debt servicing being highest after two to three quarters as floating instruments reprice at successive auctions.
The costs of servicing the debt take up a large share of the federal budget. Despite three consecutive years of contractionary fiscal policy delivering consistent primary surpluses, debt servicing consumes 40 per cent of the federal budget. The government had no choice but to cut development spending and investment in productive capital.
An anti-price policy, used to control prices, ends up increasing fiscal pressure, deteriorating the composition of public finances, and consuming public investments that can no longer be used for long-term structural productivity spending.
This structural problem would need to be significantly addressed by improving sovereign debt indicators. The Debt Management Office has achieved good results in the past few years, with its efforts to reprofile domestic maturities, increase fixed-rate debt issuances, and extend the average maturity of the public debt stock. However, the sovereign portfolio is still quite sensitive to repricing risk.
Added to these fiscal weaknesses are the severe climate and geopolitical vulnerabilities facing Pakistan. It is still one of the most climate-sensitive countries in the world and continues to suffer from devastating floods, heatwaves, and yield losses that displace millions of people, destroy infrastructure, trigger food inflation, and erode fiscal buffers.
The current adaptation and mitigation actions are not adequate in view of the magnitude of the challenge. There is an urgent need to build dedicated infrastructure for climate change adaptation, modernise water management, improve storage logistics, and make agriculture climate-smart in Pakistan to reduce vulnerability to frequent environmental shocks.
At the same time, Pakistan has to deal with its extreme geoeconomic vulnerabilities in a fracturing global order. The domestic economy is highly vulnerable to cross-border commodity price fluctuations, given its high reliance on imported fuel. The geopolitical and climate vulnerabilities have resulted in stagflationary pressures, leading to severe episodes of macroeconomic instability.
The need to protect the economy requires proactive fiscal measures to overcome acute climate and geopolitical vulnerabilities, as recurring price spirals are not the result of runaway domestic demand but of price disruptions from outside the economy.
State agencies need to invest in climate-smart agricultural infrastructure, streamline storage logistics, and limit dependence on imported energy to shield the real economy from likely and unpredictable supply-side shocks. The Debt Management Office, on the other hand, should continue working on structural reprofiling, which involves increasing the proportion of fixed-rate debt and lengthening debt maturities, to address the sovereign portfolio’s repricing sensitivity.
The government has to address these structural and debt-market fault lines, so that conventional monetary interventions will no longer exacerbate the sovereign’s fiscal difficulties.
Khanzaib Ahmad is a co-developer of the Monetary Policy Uncertainty Index for Pakistan and an analyst at Chase Securities. Abdul Moeez Mirza is a research assistant at IBA School of Business Studies
Published in Dawn, The Business and Finance Weekly, September 7th, 2026