THE State Bank of Pakistan (SBP) announced a nine-pillar policy for promotion of Small and Medium Enterprise (SME) finance in December.
On Jan 4, the SBP governor, while chairing a meeting with the chambers of commerce and trade associations of Sukkur and neighbouring areas, urged the business community and all commercial/Islamic and microfinance banks to ensure smooth implementation of the SME finance policy announced by the prime minister.
The policy is intended to boost SME financing through improving regulatory framework, devising risk mitigation strategy and simplifying procedures.
To understand the exclusion of priority sectors from the formal financial sector, we need to not only recalibrate the existing banking model but also look at the exclusion in social and contemporary policies context.
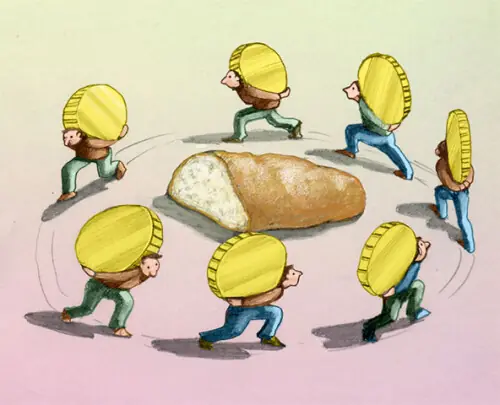
Over the last two decades private credit to gross domestic product (GDP) in Pakistan has declined. Lending is heavily skewed towards big corporations as a small percentage of borrowers are getting a major chunk of available credit, and a lot of businesses and individuals are excluded from the financial sector.
Despite the financial inclusion policy this skewed distribution of credit has not changed much over the past 10 years. A lot has been said about the processes that exclude marginalised individuals and sectors, however less has been highlighted about the behaviour that results in voluntary exclusion of entrepreneurs.
A Gallup survey found that 14pc Pakistanis use a traditional bank account while 3pc use a mobile account. However, approximately less than 1pc Pakistanis are taxpayers; the fault lies with tax-evasive culture.
Many SMEs comprise proprietors or partners who prefer to avoid inclusion in the tax net and documented economy. The most challenging areas of financial inclusion are reforms, deprivation and “self-exclusion”. In order to incentivise SME sector’s inclusion, various tax-relief measures have been suggested by the SBP to the Ministry of Finance.
The SBP has directed financial institutions to provide complete non-financial advisory services to SME borrowers. Inferior business planning and improper accounting and human resources development, operations, and marketing lead to low productivity, low level of profitability, and poor risk, resulting in adverse coverage of institutional credit.
On the demand side, banking exclusion is generally considered a result of instead of a source of social problems like low savings or unwillingness of inclusion in the formal economy by choice.
On the supply side, banks’ reluctance to lend to riskier sectors is partly due to risk-based capital requirements imposed by SBP, legal framework deficiencies and low capacity-building on banks’ end. In the Policy for Promotion of SME finance the SBP has increased the existing upper limit for retail exposure from Rs75 million to Rs125m as a relief to banks, so that SMEs can enjoy the preferential risk-based capital requirements of 75pc.
Lazy banking is the conservative risk-averse lending behaviour of banks on the supply side of loan. This behaviour stems from judicial inefficiency and strengthens collateral requirements.
Financial inclusion is not about easy access to financial systems; it is about the appropriateness of available financial products and services. For consumers, products offered need to be responsibly designed.
The writer is a visiting faculty member at PAF Kiet
Published in Dawn, The Business and Finance Weekly, January 22nd,2018