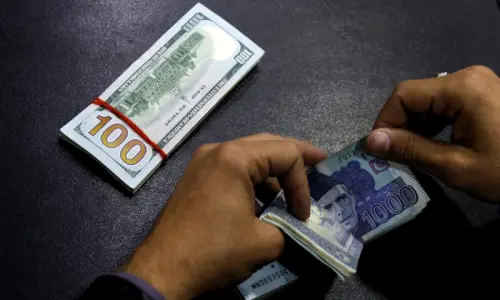
Currency in circulation, that witnessed high growth in the last few years, has started declining during the current fiscal year, thus decelerating the reserve money growth.
Reserve money has a rather more direct impact on inflation than the ordinary broad money expansion.
But whether the currency in circulation (CIC) deceleration is just a temporary aberration from a long-set trend or an indicator of a reversal in the trend is a question worth examining. Also worth examining is whether the contraction seen so far in reserve money (RM) may dampen inflation to below the extent thought necessary to fuel economic growth.
In about three and a half months of this fiscal year (between July 1, 2015 and Oct 14, 2016), increase in CIC was recorded at Rs141.5bn, down from Rs375.6bn in the year-ago period. In FY16, CIC inflows had soared to Rs779bn from just Rs377bn in FY15.
“It is too early to say CIC contraction seen so far (in FY17) is a trend-setter, reversing the last year’s phenomenal growth in it,” opines a senior central banker. “But there are reasons to believe that increase in CIC this year would be lesser compared to the last year.”
SBP sources rule out, at least for the time being, the assumption that a very low growth in money supply may actually be a pointer to some economic contraction in the making
In FY16, CIC as percentage of broad money expansion (M2) had shot up to 50pc of M2 against the last five-year average of 22.5pc. This happened due to a lot of reasons, the most important being political uncertainty, the government move to tax all banking transactions of non-tax filers, a boom in the real estate market that thrives on black money and unusually large investment in prize bonds. (Investment in prize bonds is counted outside broad money or M2 but is included in M3 which is a wider scale of measuring total money supply).
Some cooling in political temperature in the first quarter of FY17, the government’s backtracking from its move to tax all banking transactions of non tax-filers, somewhat subdued activity in the real estate sector and a more effective check on money laundering; all have played their part in keeping growth in CIC under check so far. They say that the contraction seen in reserve money growth — chiefly due to slower expansion in CIC — might also dampen the inflationary trend with a time lag.
“But much depends on the level of political uncertainty (that has risen again with Imran Khan’s PTI and the federal government seemingly headed towards a showdown next month), production of major food crops, and output of industries producing items of daily use,” says a former executive director of the SBP.
Growing political uncertainty almost always leads to inflationary expectations which have a nastier impact on headline inflation than on other factors. Low levels of supply of food and other essential items, too, swing inflation upwards. “So, the gains of contraction in reserve money, even with a time lag, are not guaranteed”, he concludes.
The SBP’s monetary policy does not have the single purpose of containing inflation. The SBP is mandated to keep inflation in check and facilitate economic growth. Our central bank aims at meeting the twin objectives by using M2 as a secondary target i.e. it tries to keep M2 growth at a level required to meet the primary targets of economic growth and inflation.
This is why the SBP remains vigilant about, and watches closely the movements in, M2 and its components, central bankers explain.
Unlike the deceleration in CIC and in reserve money, the rate of expansion in M2 so far this fiscal year has remained merely adequate, central bankers point out citing official data. Between July 1, 2015 and Oct 14, 2016, M2 has recorded a growth of 0.27pc against that of 0.11pc in the same period of the last fiscal year.
Due to the cyclical nature of banks’ lending activities and in the light of some other factors, like the government appetite for bank funds and net forex inflows, M2 growth so far is OK, they say adding that its growth must shoot up in the next three quarters to end in double digits, preferably around 13-14pc. That’s necessary to achieve the targeted level of economic growth and headline inflation.
They rule out, at least for the time being, the assumption that a very low growth in money supply may actually be a pointer to some economic contraction in the making.
We normally see M2 growing faster from the second quarter of the year that lasts till the final quarter. Let’s wait for the second quarter data, if that too indicates more than desired contraction in money supply we will examine it to find out if that, in any way, is a pointer to economic slowdown, central bankers say.
Another important thing, they point out, is that since CIC expanded in an unusually big way in FY16, a big chunk of money is going to come back into the banking systems in the next fiscal year, thereby adding to the stock of money supply to the levels required for maintaining the targeted economic growth.
Published in Dawn, Business & Finance weekly, October 31st, 2016