Analysis: Why lower inflation still feels expensive
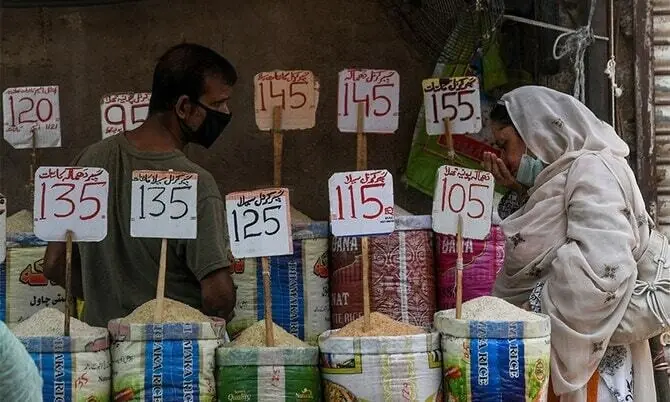

A SLOWDOWN in inflation may offer some statistical relief to the government, but prices of everyday essentials remain substantially higher than they were two years ago. The apparent contradiction lies in the difference between what inflation measures and what consumers experience when they enter the market.
Headline inflation measures how quickly the overall price basket is changing. It does not show how far the general price level has already risen. The official measure is based on prices collected from different markets and cities and combined into urban, rural and national indices. Therefore, a national average may not correspond to the retail price paid by an individual consumer in a particular market.
Lower inflation does not mean prices have returned to previous levels. It simply means that they are rising more slowly on average. Consumers continue to bear the cumulative impact of price increases recorded in previous years. This helps explain why easing inflation has yet to translate into a comparable reduction in the cost of living.
A comparison of Pakistan Bureau of Statistics prices between October 2024 and October 2026 illustrates the extent of that accumulated burden. Several essential food and energy items remained substantially more expensive than they were two years earlier, even though headline inflation later moderated. Among the sharpest increases were those in onions, electricity, diesel and petrol.
Slower inflation masks cumulative rise in essential prices over past two years
These individual price movements do not, of course, represent overall inflation, which is calculated from a weighted basket of goods and services. But they help explain the disconnect between official inflation readings and what consumers encounter in retail markets.
Wheat flour provides one of the clearest examples. The national average price of a 20kg flour bag increased from Rs1,835 in October 2024 to Rs2,697 in October 2026 — an increase of 47 per cent.
Beef with bone became 26.7pc more expensive, while the price of a 2.5kg tin of vegetable ghee rose by 18.5pc. Retail prices in individual markets can be even higher than these national averages.
The increases were steeper in transport fuels. Petrol rose from Rs248.18 per litre in October 2024 to Rs389.51 in October 2026, an increase of 56.9pc. High-speed diesel increased from Rs252.43 to Rs402.53 per litre over the same period, a rise of 59.5pc.
This is where the distinction between inflation and the price level becomes especially important. Inflation captures the pace at which prices are changing across a weighted basket. By contrast, consumers confront the actual price level when buying flour, meat, fuel and other necessities.
Several factors are contributing to the current price pressures, but former economic adviser to the government Dr Ashfaq Hasan Khan attributes them largely to higher global energy prices and domestic food prices, particularly wheat.
He said higher energy prices were a global phenomenon, but governments elsewhere had sought to cushion consumers by reducing the incidence of taxation. In Pakistan, he argued, the impact of higher international energy prices had been compounded by the petroleum levy.
“The petroleum levy is the root cause of rising inflation in Pakistan, besides higher global energy and food prices,” Dr Khan said, referring to a levy of Rs85 per litre.
He described the current pressures as predominantly from the supply side rather than the result of excessive consumer demand. That distinction matters for the choice of policy response, he argued.
“IMF is pressurising Pakistan to devalue its exchange rate and also increase SBP policy rate,” he said.
Under a conventional IMF stabilisation programme, tighter monetary policy is used to curb demand, helping contain inflation and ease balance-of-payments pressures. But if inflation is being driven mainly by energy costs, petroleum levies and food prices, higher interest rates do not directly address the underlying sources of the increase, Dr Khan argued.
“Raising interest rates is not the right solution to supply-side inflation,” he said, referring to the IMF demand for an increase in interest rates.
Published in Dawn, October 4th, 2026