US’s Fed and Pakistan’s dilemma
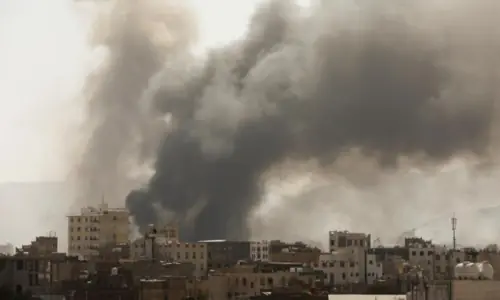
President Trump’s tariff policy and the Middle East war have made the Federal Reserve’s (Fed) job harder. Energy costs are up, tariffs are still working their way through prices, and inflation refuses to come down to target even as American hiring slows. The Fed is stuck: hold rates high and risk choking off growth further, or ease policy and risk letting inflation take root just as growth weakens into something closer to stagflation.
The July numbers explain the bind. Inflation is still well above the Fed’s 2pc target, and producer prices rose 4.7pc year-on-year, a sign the pressure hasn’t cleared the pipeline yet. The labour market, meanwhile, is losing steam, which makes another rate hike a genuine risk rather than a routine tightening move. Nine members of the Federal Open Market Committee voted in July to hold the rate at 3.50–3.75pc; three wanted a quarter-point increase; nobody argued for a cut. Markets now expect rates to stay higher for longer, with tariffs, AI-linked investment spending and Middle East-driven fuel costs all cited inside the Fed as reasons inflation could prove stickier than hoped.
The Fed therefore appears to be facing a choice in which neither direction is particularly attractive. Cutting rates prematurely could allow inflationary pressures to become entrenched, while raising rates when employment is weakening could impose damage on the economy. Keeping rates unchanged may be the only sensible option — at least in the immediate future, even though markets anticipate them to rise given expectations that inflation could remain difficult to control due to Trump tariffs and heavy investment in artificial intelligence with the Middle East conflict adding to concerns by pushing up fuel prices.
None of this stays confined to the US. Higher-for-longer rates make dollar assets more attractive, which pulls capital away from emerging markets and keeps their currencies under pressure. Add a weak global growth backdrop and countries dependent on external financing end up squeezed from every direction at once: costlier borrowing, softer export demand, a stronger dollar, and jumpy commodity prices. The Middle East war further complicates the situation as energy prices remain elevated.
Despite the credit-rating progress the country has made, prolonged high US rates will keep borrowing costs elevated
Not all emerging markets, however, would be affected equally. Countries with strong foreign-exchange reserves, deeper domestic capital markets, lower external debt and large domestic economies would have greater capacity to withstand prolonged US monetary tightening. Economies with weak reserves, large current-account deficits, high dollar debt and substantial refinancing requirements would be considerably more vulnerable.
Pakistan sits closer to the exposed end of that spectrum than the sheltered one. Reserves are still being rebuilt largely through fresh borrowing rather than exports or foreign investment, and external debt remains heavy.
Speakers at last month’s Pakistan Banks’ Association conference made the point plainly: whatever credit-rating progress Pakistan has made, prolonged high US rates will keep its own borrowing costs elevated, and that complicates the commercial financing leg of the International Monetary Fund (IMF) programme.
A firmer dollar adds a second layer of pressure by pushing up the rupee cost of servicing existing external debt. If Gulf tensions keep oil elevated at the same time, Pakistan could be paying more for imported inflation and for financing simultaneously.
Reserve-building has to shift away from rollovers and fresh IMF tranches towards non-debt inflows
There’s a way this goes better. If US inflation eases enough for the Fed to start cutting without a hard landing, the dollar weakens, global borrowing gets cheaper, and capital tends to drift back towards emerging markets — Pakistan included.
But it depends entirely on what forces the cut. A cut that comes from falling inflation and a soft landing is genuinely good news. A cut forced by a US recession is not: weaker global trade and falling commodity demand would eat into whatever relief cheaper money provides.
The Fed’s dilemma could therefore become a global one. For now, the more realistic planning assumption for vulnerable emerging economies is a long stretch of Fed caution rather than a quick pivot either way. That means they should treat expensive global capital as the baseline for the medium term, not a temporary condition to wait out. For Pakistan, this puts the emphasis back on reserves, current-account discipline, export growth and locking in longer-term, concessional financing while the window is open.
In practice, that requires reforms rather than intentions. Reserve-building has to shift away from rollovers and fresh IMF tranches towards non-debt inflows: FDI in export-oriented manufacturing and IT, not just portfolio flows chasing high domestic yields.
Current-account discipline means resisting import-led growth spurts once GDP picks up, particularly on energy and consumer goods. Export growth needs sustained real depreciation, energy-cost relief for exporters, and market diversification beyond textiles and the EU-US axis. And financing strategy should prioritise concessional, longer-tenor multilateral debt over expensive commercial borrowing, even where that means slower disbursement.
The writer is a Dawn staffer
Published in Dawn, The Business and Finance Weekly, August 24th, 2026