FCC rules income tax on immovable properties ‘confiscatory in nature’

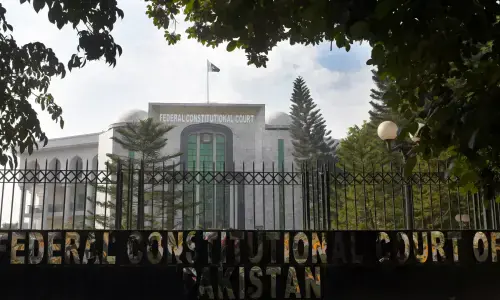
ISLAMABAD: The Federal Constitutional Court (FCC) on Tuesday ruled that Section 7 E of the Income Tax Ordinance (ITO) 2001 was merely illusory since it was confiscatory in nature, imposed upon immovable properties, which neither generate income nor, in certain cases, are capable of generating any income.
“The practical effect of such a levy is that a person owning a non-income-generating asset may be compelled to dispose of the asset to meet tax liability,” observed Chief Justice FCC Aminuddin Khan.
The judgement came on the day when parliament was debating the finance bill 2026, which includes proposals to implement the May 7 short order in which the FCC had declared Section 7E ultra vires. This section, introduced through the Finance Act 2022, empowered authorities to charge tax on “deemed incomes” on assets and properties.
The levy under section 7E operates in a discriminatory manner as it carves out exemptions in favour of certain classes of persons, thereby subjecting similarly placed taxpayers to unequal treatment, emphasised the CJ. The detailed reasons noted that the provision does not withstand constitutional scrutiny since it falls outside the legislative competence of the federal legislature.
Justice Aminuddin notes tax raises legitimate concerns regarding excessive fiscal burden, economic redundancy
“Where a levy is structured in a manner that taxes both the source of acquisition and thereafter the asset itself without reference to income generation, it raises legitimate concerns regarding excessive fiscal burden and economic redundancy,” observed Justice Aminuddin Khan, who had headed a two-judge Supreme Court that decided several petitions filed by a number of taxpayers against the judgements of the Sindh High Court (SHC) and the Lahore High Court (LHC) as well as the Federal Board of Revenue/Commissioner Inland Revenue (CIR).
The detailed reasons noted that subsequent to the 18th Amendment, similar disputes had assumed increased frequency, primarily owing to overlapping assertions of fiscal authority by the federation and the provinces.
The consequence, in a number of such cases, is that the taxpayer is compelled to engage in unnecessary and protracted litigation, often being exposed to the risk of double taxation in respect of similar subject matter.
This state of affairs not only places an undue and disproportionate financial burden upon taxpayers, but also results in avoidable strain upon the constitutional jurisdiction of the superior courts, manifested through a proliferation of constitutional petitions, CJ-FCC regretted.
Such a course is neither conducive to fiscal certainty nor consistent with principles of fairness and orderly tax administration.
Though the legislature is competent to classify persons or properties for the purposes of taxation, such classification must satisfy the test of reasonableness, the FCC said.
Where exemptions are granted without any discernible principle, or where the classification is arbitrary, artificial, or discriminatory in effect, the same cannot withstand constitutional scrutiny, the FCC emphasised.
He said Section 7 E was violative of the fundamental right guaranteed under Article 23 of the Constitution, which secures to every citizen the right to acquire, hold, and dispose of property.
Before concluding, the FCC also settled the objection regarding the constitution of the bench, contending, with reference to the Supreme Court Rules, 1980, that the present matter ought to have been heard by a bench comprising not less than three judges, whereas the case was being adjudicated by a two-judge bench, allegedly in violation of the applicable procedural framework adopted by the FCC.
While overruling, the FCC explained the objection was devoid of substance since after its establishment, it had adopted the Supreme Court Rules 1980 and accordingly modified Order XI through Dec 2025 notification.
It is a settled principle that the constitution of benches is the exclusive prerogative of the chief justice, who is the master of the roster, the judgement said, adding that in the absence of any express statutory or constitutional mandate requiring a bench of a specified numerical strength for the adjudication of the present lis, a bench comprising two members cannot be held to be incompetent.
Published in Dawn, June 17th, 2026