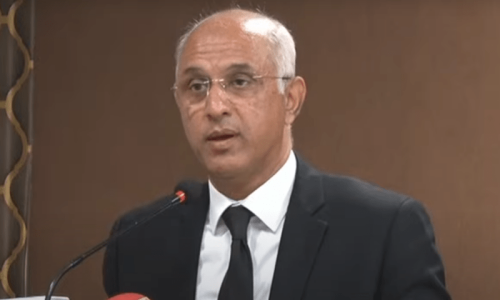
FINANCE MINISTER Ishaq Dar has once again sought to quash speculation that Pakistan could default on its foreign debt obligations. Speaking to investors via video link, he admitted that the economy was in a “tight spot”, but added that the fears of defaulting had no basis whatsoever. “Not a day passes that I don’t hear speculations of a default. There’s no chance of Pakistan defaulting on its debt payments,” he contended. To press his point, he said there were several other economies, including the US, the UK and Japan, that had a far worse debt-to-GDP ratio than Pakistan’s 72pc, and yet no one believed these countries would default. Indeed, the likelihood of Islamabad missing its debt payments in the short to medium term is minimal. Nor is the comparison between Pakistan and Sri Lanka, one of the four countries to have defaulted on their sovereign debt, valid at this stage. In spite of a difficult domestic macroeconomic environment caused by fiscal profligacy and massive import growth, and exacerbated by uncertain global economic and political conditions, the present government has managed to stave off the risk of default by reviving the IMF loan programme, notwithstanding the current hurdles. Credit must also be given to the coalition set-up for taking certain unpopular decisions that significantly eroded its political capital.
Nonetheless, no minister or other government official can blame the opposition PTI for its consistent narrative of a potential default. There are legitimate reasons that the default debate refuses to die down. The top global rating agencies have already downgraded Pakistan’s ratings to junk territory. Forex reserves continue to shrink and the exchange rate remains under pressure despite stringent curbs by the State Bank to reduce the nation’s burgeoning import bill. Commercial creditors have turned down requests to roll over debt, at least for now. Various international agencies have projected that Pakistan could face a severe currency crisis in the next 12 months. The IMF has twice postponed its next programme performance review, delaying the disbursement of the $1.2bn tranche. Other multilateral and bilateral creditors aren’t delivering on their commitments due to Islamabad’s ongoing tensions with the IMF on unmet programme targets. Unless investors see a reversal in these trends, the market will continue to worry about Pakistan’s ability to repay its debt. Fixing our relationship with the Fund would be the first concrete step towards quashing the default rumours once and for all.
Published in Dawn, December 29th, 2022