The State Bank of Pakistan (SBP) confirmed on Thursday that Pakistan has received $2 billion from the Kingdom of Saudi Arabia.
The central bank said the funds were received “in the value date of April 15, 2026”.
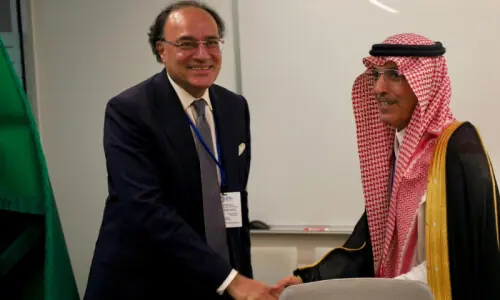
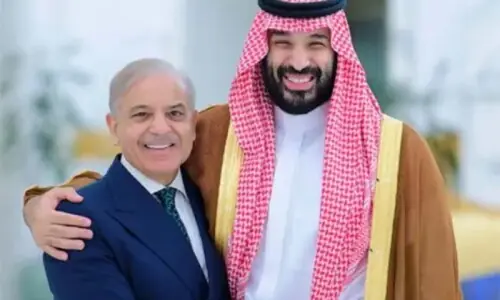
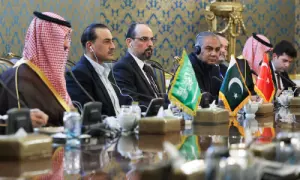
The development comes amid Prime Minister Shehbaz Sharif’s visit to Saudi Arabia to push diplomatic efforts to promote peace in the Middle East.
A day earlier, the kingdom pledged an additional $3bn in deposits for Pakistan and extended its existing $5bn facility for a further three years.
On Thursday, the Saudi Press Agency also reported that Saudi Arabia had extended the $5bn deposit with the central bank and announced an “additional $3bn deposit”.
“This assistance aims at supporting Pakistan’s economy and strengthening its resilience amidst evolving global economic challenges, and comes in accordance with the leadership’s directives to strengthen the bonds of brotherhood between the two countries, affirming the kingdom’s commitment to fostering the economic growth of Pakistan, which is expected to reflect positively on the living conditions of Pakistani citizens,” it said.
Finance Minister Muhammad Aurangzeb said earlier that the existing $5bn Saudi deposit would no longer be subject to the previous annual rollover arrangement and would instead be extended for a longer term.
Pakistan will reportedly return a $3.5bn loan to the UAE this month, putting pressure on its reserves and risking breaches of its International Monetary Fund (IMF) programme targets.
The development comes at a sensitive time for the country’s external account position, which is already under strain from rising global oil prices and economic spillovers linked to tensions in the Middle East.
According to official figures, Pakistan’s foreign exchange reserves stood at $16.4bn as of March 27, sufficient to cover close to three months of imports. However, the repayment requirement from the UAE has added fresh pressure on the country’s external buffers.
In March, Islamabad failed to secure an agreement with the UAE to roll over the $3.5bn facility, marking the first such failure in seven years and raising concerns about near-term financing gaps.
Pakistan’s foreign exchange position, though under pressure, remains part of a broader stabilisation effort under IMF-supported reforms.
Analysts say external financing risks remain a key vulnerability, particularly amid volatile energy prices and constrained global capital markets.